
What is one thing the OBBBA Tax Changes have in common with the Alps?
Today, I’m going to answer that riddle. I’m also going to highlight the key issues from the new tax bill:
- What are the big wins for retirees?
- What changes may hurt early retirees?
- What the new law means for retirement planning.
But first, a story of my recent Pre-Go-Go adventure…
On June 29th, I left for Switzerland.
It was more than a vacation—it was my first deliberate experiment blending the final stretch of my working years with the early flavors of retirement. I’ve started calling it my “Pre-Go-Go” phase: that period before retirement where you test out what life might look like when the pace slows and priorities shift.
Since starting my business in 2011, I’ve never taken a vacation without my laptop—until this one. While I remained mostly unplugged, I used my phone to peek in on emails and Slack messages (an internal messaging app we use).
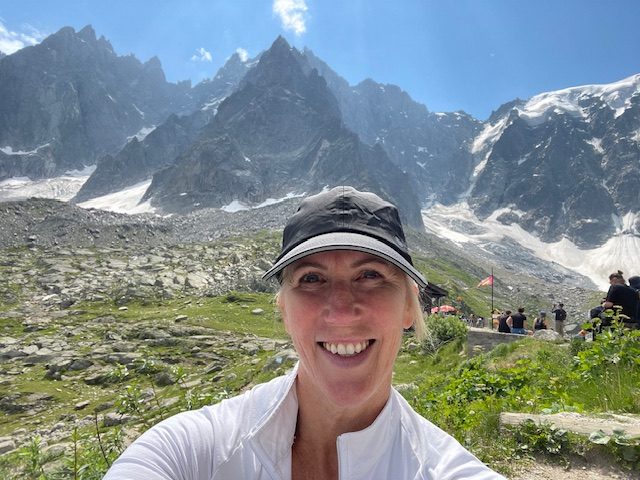
On July 1, we began our hike. Eight to ten hours a day, I was outdoors in the most beautiful country I’ve ever seen, with emails—and tax bills—far from my mind. I grew up watching The Sound of Music. Watching it on the screen and seeing it firsthand are quite different. The sheer scale of seeing mountains shoot straight up is… awe-inspiring. Our world is incredible.
Below is a picture from our first day of hiking.
The One Big Beautiful Bill Act Rolls Out
On July 3rd, our internal “Planner” messaging channel began buzzing with the news of the One Big Beautiful Bill Act (OBBBA).
“What would the team do?” I wondered.
They immediately set out to update our planning model. By Monday, July 7th, they began putting clients in the new model to understand the impact. They even wrote and sent a brief newsletter outlining a few key provisions.
I watched it all happen from afar and did not intervene. They didn’t miss a beat.
And I didn’t miss a beat either! I enjoyed my vacation and did not let the news distract me. Two and a half weeks immersed in another world did wonders for my energy and focus.
July 16th was my first day back in the office. I was ready to go back. I missed work. It felt like being away from home or family for too long. I’m clearly not ready for retirement—but I also confirmed that I need to incorporate more breaks like these. That balance is critical for me at this stage of my career.
Given all this, I label my first Pre-Go-Go trip experiment a success!
Now, on to what I (luckily) still love to do—translate financial complexity into what it means at a household level.
Digesting the New Tax Changes
My first thoughts on the OBBBA?
What a hodge-podge of random provisions! What complexity. If we thought Roth conversion analyses were difficult before… ooof (me trying to type out the sound of getting the wind knocked out of you). They just got exponentially more challenging.
For those who want a thorough technical run-down of the rules, no one does it better than the professionals who write for Kitces.com at the Nerd’s Eye View. You’ll find their write-up at Breaking Down The “One Big Beautiful Bill Act”: Impact of New Laws on Tax Planning.
For those who want a practical summary, I’ve outlined key provisions below—grouped by who benefits and who might be impacted negatively.
Let’s dive in.

Key Provisions of OBBBA
1. Universal Wins
A) Most Impactful: Tax Rates
- Impacts: Everyone
- Timeframe: 2025, no expiration
The current brackets no longer sunset, avoiding a reversion to pre-2018 levels. This one change alone is responsible for increasing “fundedness” by around 3% in most plans I’ve reviewed. (Fundedness is one of several metrics used to stress test a retirement plan.)
This positive impact comes from a reduction in households’ effective marginal rate, which reduces the present value of lifetime taxes, increasing the after-tax value of assets estimated at the end of a plan.
Or, put another way, these improved metrics offer the opportunity to spend more earlier without compromising future financial outcomes.
You may want to ask, “Rather than leave an extra couple hundred thousand when I’m 85, how much more could I spend now and still end up in the same place?”
B) Standard Deduction and Bracket Adjustments (Minor, but Beneficial)
These next two provisions also benefit nearly everyone:
- In 2025, a slightly higher standard deduction takes effect.
- In 2026, the 10% and 12% brackets expand modestly, which becomes worth a few hundred to a few thousand dollars in tax savings, depending on household income.
C) Extra Senior Deduction
- Impacts: Age 65+, MAGI < $175K* (singles), < $250K (joint)
- Timeframe: 2025 to 2028
MAGI refers to Modified Adjusted Gross Income.
Adds $6,000 (singles) or $12,000 (joint) to the standard deduction for qualifying seniors. The deduction begins phasing out at $75K (single) and $150K (joint), making Roth conversions and tax-deferred withdrawals trickier to plan when near those limits.
*Previous posted version showed this as $150k. It has been corrected to $175k.
D) Mortgage Insurance Deduction
- Impacts: Homeowners with <20% down
- Timeframe: Begins 2026
Mortgage insurance premiums become deductible again—helpful for late-start retirement savers, or perhaps those rebuilding after divorce or bankruptcy and using FHA/VA loans with less than 20% down.
E) Auto Loan Interest Deduction
- Impacts: MAGI <$150K (single), <$250K (joint)
- Timeframe: 2025 to 2028
Eligible for vehicles assembled in the U.S. and purchased with a new loan (or refinanced without increasing balance). Only the first $10,000 of interest is deductible.
I’m honestly perplexed how many households at these income levels will rack up $10K in interest. Perhaps that’s because I’m focused on retirees – a colleague reminded me that many households with teenage children have multiple cars. And who knows, maybe auto financing departments will get creative with loan packages where you pay all interest first?
F) Qualified Tips and Overtime Deductions
- Impacts: MAGI < $150K (single), < $300K (joint)
- Timeframe: 2025 to 2028
The Qualified Tips (first $25,000 of qualified tip income – same limit single or married) and Qualified Overtime deductions (first $12,500 single/$25,000 joint) are subject to eligibility requirements and phaseouts.
I see this as a win for service and blue-collar workers. Also helpful for retirees working part-time in tipped industries.
G) Charitable Deduction for Non-Itemizers
- Impacts: Non-itemizing filers
- Timeframe: Begins 2026, no expiration
Non-itemizers can deduct $1,000 (single) or $2,000 (joint) for charitable gifts. Modest, but could help households who give consistently but don’t meet the standard deduction threshold. However, this deduction, unlike the Qualified Charitable Contribution (QCD from an IRA), does not lower AGI, so it won’t help in other areas.
H) SALT Deduction Increase
- Impacts: MAGI < $600,000
- Timeframe: 2025 – 2029
Raises the SALT cap (state and local taxes) to $40,000 (phasing out at MAGI of $500K and gone by $600K). Most useful for middle-income earners in high-tax states.
The definition of “middle income,” of course, is up for debate.
I) Estate Tax Exemption
- Impacts: Ultra-high-net-worth households
- Timeframe: Begins 2026
The estate tax exemption increases to $15 million per person, starting in 2026. Great news for the next generation of a select few families.
2. Changes That May Hurt Early Retirees
A) HealthCare Tax Credit Changes
- Impacts: Pre-age 65 Marketplace Plan users
- Timeframe: Begins 2026, no expiration
We’re back to pre-2021 rules. The 8.5% MAGI cap on premiums is gone. Starting in 2026, your income must fall within the federal poverty level thresholds to qualify for Advance Premium Tax Credits.
In the past few years, I’ve seen many early retirees (in the 55 to 64 age range) qualify for substantial credits that helped cover their insurance premium costs—even though many of them had financial assets in the $1.5 to $2.5 million range. That’s because eligibility is not tied to assets but to income. And income can be managed by when and how you use various assets for cash flow.
- Before 2021, if your income exceeded the federal poverty levels (FPL – adjusted each year with inflation), you were not eligible for a subsidy to help cover the cost of a Marketplace health plan.
- From 2021 to 2025, adjustments to the formula helped more households qualify for higher credits. In 2026, those adjustments are eliminated. Less households will qualify, and those who do will see lower credit amounts.
Additional changes are beyond the scope of this summary. But it all means that starting in 2026, income projections for your Marketplace plan application will be more critical—if you overshoot, you may owe far more back when you file your tax return than in recent years.
However, there may be one silver lining: a new HSA-eligible Marketplace plan. Some households losing credit eligibility may be able to get an HSA deduction instead—if they choose their plan appropriately.
Deductions, however, are not as beneficial as credits.
B) Not Great for Gamblers
- Impacts: Itemizers with gambling activity
- Timeframe: Begins 2025, no expiration
Losses can now only offset 90% of winnings. This hits gambling retirees hard, since winnings inflate AGI but losses don’t reduce it. (And a higher AGI can result in higher taxes in many other areas.)
I’ll never forget one client I worked with, who has since passed, who had over $500,000 in gambling wins and losses on his tax return each year. That’s a lot of time at the casino. Now that same client would claim $50,000 of gross income, even though his losses equaled his winnings.
With sports betting on the rise, this may impact more people.
C) Charitable Deduction Changes for Itemizers
- Impacts: Itemizers who make charitable contributions
- Timeframe: Begins 2026, no expiration
Charitable contributions, beginning in 2026, will be subject to a .5% (half a percent) floor, with a complex set of ordering rules to follow depending on the type of donation.
For some, donating more this year may be beneficial.
In one recent client meeting, we had donor-advised fund (DAF) contributions planned for this year and next, then in 2027, donations shift to come from the IRA through Qualified Charitable Contributions as this person reaches age 70 ½ that year. Now, instead, we recommend making the 2026 DAF contributions in 2025 to avoid losing part of the deduction due to the floor next year.
In addition, in 2026, there is an itemized deduction cap, which effectively means the benefit of the deductions is capped at the 35% rate, rather than the highest 37% rate. This impacts only those with income falling in this 37% bracket.
Essentially, these rules impose both a floor and a cap on charitable deductions.
For those who regularly contribute to charity, consider accelerating any future planned large charitable contributions into 2025.
D) AMT (Alternative Minimum Tax)
- Impacts: Taxable income > $500K (single), > $1M (joint)
- Timeframe: Begins 2026, no expiration
I’m not sure if anyone knows what AMT is anymore—since TCJA (Tax Cuts and Jobs Act) changes, it impacts only about .1% (1/10 of 1%) of households. A specified amount of income is exempt from the AMT tax. But this exemption phases out as your income crosses IRS thresholds.
Now, the AMT exemption phaseout limits drop, most likely hitting those who still hold incentive stock options—uncommon since 2006 accounting-rule changes—but potentially relevant in tech-heavy or executive households. This may also impact those with large capital gains, as those gains may more easily push them into the range where they lose the exemptions.
What This Means for Planning
There are many, many other changes. The sheer scope of this bill is mind-boggling. Without software, accurately incorporating everything into a tax return is nearly impossible. Perhaps Einstein could do it.
Everyone wants a “rule of thumb” approach for what to adjust. That was hard before. Now, with multiple income cliffs and overlapping MAGI thresholds, the only realistic approach is case-by-case.
One client told us they’d heard they should accelerate Roth conversions. Maybe—for some people, in some situations. But I can’t imagine recommending that universally based on OBBBA.
Our planning team has also debated how “permanent” these changes really are. Could future legislation raise rates? Absolutely. But even then, plans still benefit from several years of lower rates.
My Universal Conclusions
There are only two things I’ve seen hold true in every single plan so far:
- OBBBA improves outcomes by a measurable margin.
- It adds immense complexity, especially around conversions and withdrawal strategies.
Oh, and I’ll add a third: it gives me one giant headache. Has anyone tried correlating Advil sales with tax bill releases?
These changes illustrate the importance of thoughtful tax planning—it’s an evolving puzzle. And the OBBBA added many new pieces.
Whether you’re still working or already easing into retirement, an updated plan may reveal more room to breathe—maybe even enough for an earlier retirement, that bucket-list Pre-Go adventure, or simply the confidence for more worry-free spending in your Go-Go years.
In the opening line, I asked a riddle. In my final line, I’ll answer it.
“Room To Breathe”
Perhaps the one thing OBBBA has in common with The Alps.
Your Turn: Have you evaluated how the OBBBA changes impact you? If so, we’d love to hear your insights in the comments.
Thank you. We love Switzerland for all the reasons you wrote. We got it our planner team and had these discussions but it’s nice to read them here so well written. I’m glad you are working with Fritz!
Nice recap Dana! We so enjoyed our time in the Alps too, especially the little Swiss village of Lauterbrennan!
I thought your riddle was going to be “soaring”! As increased debt is to the Alps! 🥴
Lauterbrunnen was the most beautiful place I’ve ever been to. The whole time we were there it was hard to believe any of it was real. We hiked up the inside of Trümmelbach Falls – there’s an elevator up it for non-hikers. I’d recommend everyone had Lauterbrunnen to their bucket list.
You have done a fantastic job to break down the complexity into a simpler, laymen terms. Great job. Also great that you get to experience what the early Go-Go years of early retirement may be like for you. Your conclusion was spot on about “Room to Breathe” for tax planning and retirement planning. I have enjoyed your takes on the most important issue for any retiree. I pray that you will soon find the life-balance between work-rest is working for you. Many thanks for your insights. Keep up the good work.
Thank you!
Hi Dana,
Did you hike the Alps with a tour group and could you provide the name of you recommend them? My wife and recently hiked the Dolomites with the Appalachian Mtn Club and we really enjoyed it so we will look for more hiking opportunities in Europe.
Thanks,
Rich
We went through Mountain Travel Sobek. (https://www.mtsobek.com/) My family has used them in the past for many treks – I did two of them in the early 2000’s – a trek to Machu Picchu and a coast-to-coast hike across England. All were fabulous! I’ve also had several clients take the National Geographic trips and they’ve reported they are amazing.
Thanks Dana!
We have hiked the Haute Route (Mont Blanc to the Matterhorn) and the Dolomites with the tour group Alpenwild – https://www.alpenwild.com/, and highly recommend them.
Thanks Jerry!
Thanks so much for the clear summary of the bill and its implications for retirees and near retirees. Enormously helpful!
Thank you! Glad to hear it is helpful.
Any thoughts about the potential increase to the deficit in order to achieve these tax cuts? I am very worried about the impact on the deficit, not to mention the cuts to SNAP and Medicaid.
When financial stimulus during the Great Recession began, everyone was certain we would have massive inflation. It was talked about like a foregone conclusion. Instead, we had a decade of incredibly low inflation. After that experience, I avoid trying to speculate on the other impacts. I know how to build a financial model and illustrate the impact over a household’s lifetime. The rest – well – I’ve seen so many knowledgeable people speculate and often reality turns out different.
It’s worth saying that there are other takes on this legislation. Non-partisan, expert estimates show millions of people likely losing access to health care, cruel reductions in SNAP (food stamps), and on the list goes. There is a simple case to be made that the net effect of this legislation is not at all good for any retirees, anywhere, whether they or members of their family and community are directly, negatively affected or not.
I totally understand. I am evaluating the impact of the new tax rules on an individual or couple’s financial situation over their projected lifetimes for a specific demographic that is over 55 and has retirement savings.
I don’t believe where you essentially said that under current tax law itemized deductions reduce a taxpayer’s AGI is a correct statement.
Line 11 on the 2024 IRS Form 1040 is your adjusted gross income (AGI), and then on line 12 either the standard or itemized deductions are then subtracted from AGI.
The standard or itemized deductions reduce taxable income, not adjusted gross income.
Isn’t that how the standard deduction and itemized deductions work before and after the OBBBA?
Ritch – you are correct! What I meant to say was “unlike the QCD (Qualified Charitable Contribution) from IRAs. My brain was stuck in thinking about itemized. We’ll correct this! Thank you!
I’m early retired and in my 50s with ACA and preexisting health issues. My strategy is to keep my taxable income at an amount needed to qualify for ACA in 2026. I’ll be pulling from non taxable accounts to make up the difference of our budget and to reach my annual cash needs. Do you have any suggested resources to help plan for this goal? My typical sources are still trying to figure things out too.
I am 62 YO and have been retired for 3 YRS. Other than the extended favorable tax rates, I receive No other benefit. The house is paid off, the cars are paid off. My wife is 57 on SSDI, so we do not receive 65+ Free Money. OBBB=Crap. Just adds to $36T Federal Deficit.
I thought Qualified Charitable Distributions might be what you had on your mind since they do reduce a taxpayer’s AGI. Thanks for the clarification. There’s a lot of confusion about whether that new tax benefit is an above or below the line deduction, as Harry Sit pointed out recently in a post on his blog about the various OBBBA provisions.
I’m glad you enjoyed your first Pre-Go-Go experience. The Sound of Music was always my wife (who passed away last August) and my’s favorite movie. Beautiful scenery and a wonderful, fact based storyline. Hollywood doesn’t make movies like that anymore, which is a shame, IMO.
Thanks for the concise summary. I walked the Alps rather that hiked!